˙⋆ data science × economics ⟡˙

Vanessa Feng

i build models that keep risk afloat.

data scientist & economist drifting through credit, portfolio & quantitative risk

psst, press b for bubbles ⟡

⋆˙⟡ a little about me

hello from the tide pool

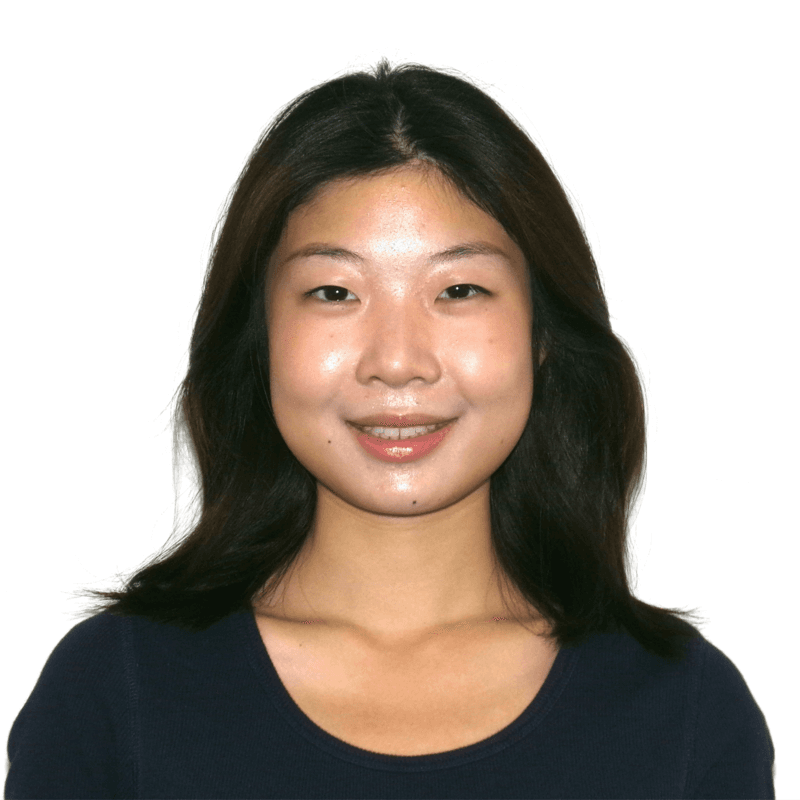
Portrait of Vanessa Feng

i’m a data science & economics student at uc san diego who likes turning messy financial data into something calm and legible. most of my work lives where statistics meets markets: probability-of-default models, portfolio rebalancing, and the quiet plumbing that helps risk teams sleep at night.

i’ve interned across asset-management, wealth-management, and credit risk (j.p. morgan, morgan stanley, lima one capital, and rappo), and i’m heading back to j.p. morgan full-time as an analyst after graduation. i care about models that are accurate *and* explainable, dashboards people actually open, and a tidy threshold that catches the right loans.

fun facts

⋆˙⟡ where i'm studying

education

University of California, San Diego

San Diego, CA · Expected Jun 2027

B.S. Data Science & B.A. Economics

GPA 3.75 / 4.0

relevant coursework

  • Econometrics
  • Financial Accounting
  • Financial Statement Modeling
  • Data Modeling
  • Machine Learning & Application
  • Data Management
⋆˙⟡ where i've worked

a string of pearls

  1. J.P. Morgan

    Asset Management Summer Analyst

    New York, NY · Jun 2026 – Aug 2026

  2. Morgan Stanley

    Wealth Management Intern, Portfolio Risk Management

    New York, NY · Aug 2025 – Sep 2025

  3. Lima One Capital

    Credit Risk Intern

    Greenville, SC · May 2025 – Aug 2025

  4. Rappo

    VC Analyst Intern

    San Francisco, CA · Jun 2024 – Sep 2024

⋆˙⟡ things i've built

treasures from the reef

Jan 2024 – May 2024 · San Diego, CA

Probability of Default Predictive Model

An end-to-end credit-risk model that scores default risk for credit-card holders and informs mitigation strategy.

  • Logistic Regression
  • Python
  • Credit Risk
  • WoE / IV
  • Vintage Analysis
  • Model Validation
  • Logistic-regression PD model built end to end, from raw credit-card data to a validated, monitored score.
  • Vintage and roll-rate analysis to set the performance window and track how delinquency moves over time.
  • Feature selection with Weight-of-Evidence / Information Value, stepwise regression, and clustering, narrowing a wide feature set to a handful of strong predictors.
  • Validated for discriminatory power, stability, and accuracy, with warning and breach thresholds for ongoing monitoring.
⋆˙⟡ my little toolkit

shells in my collection

technical

  • Python
  • Java
  • SQL
  • Tableau
  • Snowflake
  • Excel
  • PowerPoint

finance & risk

  • Credit Risk
  • Portfolio Risk
  • Monte Carlo Simulation
  • Financial Modeling
  • PD Modeling
  • Sensitivity Analysis

certificates

  • Securities Industry Essentials (SIE)
  • Bloomberg Finance Fundamentals
  • Goldman Sachs Excel Skills for Business
  • Financial Reports Analysis

languages

  • English (native)
  • Chinese (native)
  • French (intermediate)
⋆˙⟡ let's float together

say hello

drifting in from a recruiter, a classmate, or just curious? say hi! i’m happy to talk risk, models, or tide pools.